Testing the floor

Commentary, Sep 21, Jos Algra

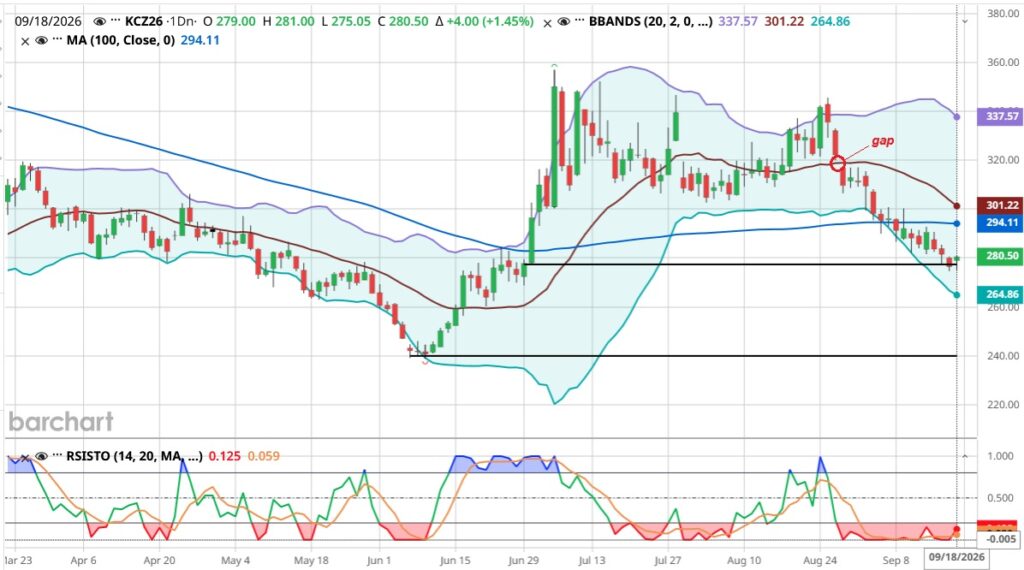
New York coffee prices continued their downward trend, breaking the 280 support level and touching a low of 274.60 on Thursday—the lowest price in two and a half months. On Friday, the price recovered 4 points to close at 280.50.

Coffee prices are facing increasing pressure from Brazil’s large harvest volume. The ICO also forecasts a surplus of 3 million bags—the first in five years. In August, Brazil exported 4.2 million bags, the highest level on record for that month.

On the other hand, certified New York inventories fell to 217,646 bags on Tuesday—a 27-year low—but by Friday, they had risen to 258,415 bags, surpassing levels seen a month and a half ago.

The New York market is heavily oversold—a condition that has persisted for nearly a month without triggering a price correction or a market rebound.

The 280 floor has been breached in recent days. It remains to be seen whether the support level around that mark can hold following Friday’s slight recovery. If not, prices could drop to the 260 and 240 levels.

To move higher, the price must first break above the 100-day moving average, currently at 294.10 cents.

Support: 274.60, 260.15, and 238.85. Resistance: 292.50, 300.25, and 316.90–319.80 (gap).
According to the Commitment of Traders report, combined futures and options Open Interest fell by 8,593 contracts over the last two weeks, dropping from 200,891 to 192,298. Futures-only open interest decreased by 3,680 contracts, from 155,275 to 151,575 as of last Thursday. Daily volume averaged 29.5 thousand contracts (ranging from 24.1 to 41.4 thousand).

The funds’ net position shifted by 8,861 contracts, moving from a net long of 7,145 to a net short of 1,716. Except for a brief moment in June of this year, funds have maintained a net long position since October 2023. Spreads – reflecting the extent to which non-commercial traders hold combined long and short positions – decreased by 6,952 contracts, falling from 72,227 to 65,275.

Commercials’ long positions rose by 3,334 lots, from 51,651 to 54,985, while their short positions fell by 6,950 lots, from 96,697 to 89,747.

Index funds reduced their net long position by 517 contracts, dropping from 35,654 to 35,137.

There is a palpable shift in the atmosphere of the New York market. After three years, funds have abandoned their bullish bets and adopted a net short position. Roasters continue to capitalize on the price drop to lock in contracts. Producers are further reducing their price fixings amidst the decline; they were forced to fix against the September contract and will eventually have to fix contracts against the December position. Many have incurred—and continue to incur—significant losses by delaying their price fixations, waiting for a price recovery. 

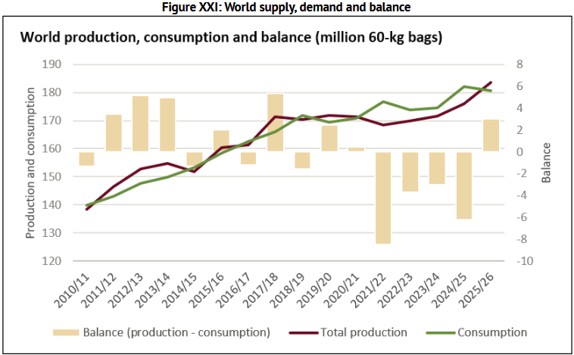
In its August report, the ICO notes that in 2025/26, production increased by 4.4% to a record volume of 183.6 million bags. Consumption fell by 0.9% to 180.6 million, resulting in a surplus of 3 million bags—the first surplus in five years.
In our previous blog post, The error we analysed Brazil’s monthly and annual export volumes. Due to a “system error” at Cenicafé, the projected export figure for August initially stood at under 3 million bags. Once the “error” was corrected, the figure jumped to nearly 3.8 million and subsequently to 4.0 million.

Updated data from Cenicafé now show that the August volume was even higher: 4.2 million bags, a 31% increase over August of last year and a 36% rise compared to July. This represents the highest volume ever recorded for the month of August across all categories: Arabica (2.9 million, +26%), Robusta (1 million, +54%), and 300 thousand bags of soluble coffee. The previous record was set in August 2024, with 3.8 million bags.

Conditions in Brazil remain favourable during this critical flowering stage, though the El Niño phenomenon could alter the outlook. Vietnam is increasing production for the 2025/26 harvest by 6%, reaching 29.4 million bags. Exports rose by 17.5% to 26.3 million in 2025, with an additional 13.7 million exported between January and August of this year, bringing the total to 22.2 million. As with Brazil, there is significant uncertainty regarding the impact the developing “Super El Niño” will have on the new crop cycle.

Producers in Peru have reported that the price differential for Grade 1 coffee has risen to +70/+80, though exporters state that no one is actually paying that rate. Faced with coffee shortages and high prices in Peru, buyers are turning to Honduras and the rest of Central America.

There are problems with the bookings, because the Panama Canal has a reduced capacity to lock ships through due to the draught and coffee is accumulating at the mills and ports, notwithstanding the reduction in production. 

Researchers from the University of Viçosa and the Federal Institute of Espírito Santo have discovered bacteria capable of fixing atmospheric nitrogen, solubilizing phosphorus, and producing plant hormones. This discovery could potentially replace synthetic fertilisers, thereby reducing both environmental and financial impacts. 

Two farms in Minas Gerais growing the same Yellow Catua coffee variety were compared over a period of more than fifteen years. One uses chemical fertilisers, while the other uses chicken manure. Thirty-eight bacterial strains were identified, including some local ones that were previously unknown. The organic method enriched the soil with genera that were absent from the chemically fertilised soils.

See Brazilian Coffee Soils Harbor “Hidden Bacteria” That Could Revolutionize Sustainable Farming.

Jos Algra is an international consultant with more than 40 years of experience in coffee and working with producer organisations.

This blog was originally published in Spanish in Claase:

https://claase.org/analisis-de-los-precios-del-cafe

El error

Comentario, 5 de sep, Jos Algra

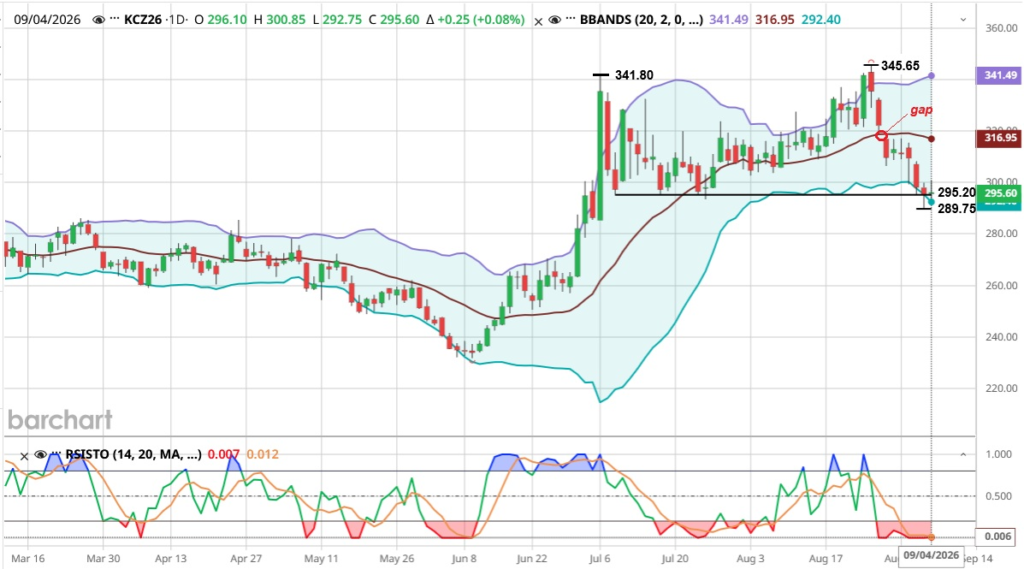
El pecio de café posición diciembre en Nueva York subió a un máximo de 345.65 martes 25 de agosto, el precio más alto desde el 6 de julio. Sin embargo allí el precio topó y el mismo día perdió 6.15 centavos en el cierre. Miércoles fue peor con una pérdida de 13.35 centavos y jueves otros 12.50. Siguió cayendo hasta un mínimo de 289.75 el jueves 3 de septiembre. Viernes 4 se paró la caída por el momento, el precio subió ligeramente y cerró en 295.60.

El precio de café está bajo presión del gran volumen de cosecha en Brasil que ha concluido y que puede ser mucho mayor de lo pronosticado. La fuerte caída del miércoles 26 de agosto se adjudica a la corrección de un “error” en el sistema de Cecafé, con que resultó de repente que Brasil en agosto de repente exportó 1 millón de sacos más. 

El precio de Arábica en Nueva York llevó a rastras el Robusta en Londres, que rompió el piso de 3,600 dólares por tonelada y cerró el viernes en 3,430 $/TM.

La primera pregunta es si el piso de 295.20 va a aguantar; ya se ha intentado 3 veces romperlo, incluyendo jueves y viernes. Si se rompe puede el precio puede caer a 285.25, 263.50, y eventualmente 231.80 centavos. El mercado está muy sobrevendido, como muestra el estocástico, lo que puede dar lugar a una retracción.

Hacia arriba está resistencia en el gap (brecha) de 316.90-319.80. En teoría las brechas siempre tienen que ser cerradas, es decir el precio tiene que subir a ese nivel, porque quedaron órdenes de compra y venta pendientes de ejecutar. En la práctica no siempre sucede, puede tardar días, semanas o hasta meses hasta que se cierre.

Soportes: 295.15-295.20, 289.75, 285.25, 263.50, 256.90, 250.55 y 231.80. Resistencias: 316.90-319.80 (gap) y 345.65.

En el Commitment of Traders report interés abierto de futuros y opciones combinados bajó en las últimas 2 semanas 1,373 contratos de 202,264 a 200,891. El interés abierto de solo futuros bajó 9988 contratos de 156,273 a 155,275 el jueves pasado. El volumen diario promedió 29.5 mil contratos.

La posición neta larga de los fondos, bajó 7,899 contratos de 15,044 a 7,415. Los spreads, que reflejan el grado en que cada operador no comercial mantiene posiciones largas y cortas combinadas, bajaron 860 contratos de 73,087 a 72,227.

La posición larga de los comerciales subió 2,119 lotes a de 49,532 a 51,651. La posición corta de los comerciales bajó 4,312 lotes de 101,009 a 96,697. 

Los fondos de índice aumentaron su posición neta larga con 1,540 contratos de 34,114 a 35,654.

Los están bajando sus apuestas al alza. Los tostadores están aprovechando la baja del precio para fijar contratos. Los productores están bajando sus fijaciones ante la caída del precio, pero en algún momento van a tener que fijar los contratos contra posición diciembre. Muchos habrán perdido mucho por haber esperado con fijar, esperando una mayor alza del precio.

En el blog del 23 de agosto El cambio se acecha comenté que las exportaciones de Brasil parecían quedarse en alrededor de 3 millones de sacos en agosto, igual que en julio y por debajo del volumen mensual de marzo a junio. Pues nada podría estar más lejos de la verdad, el aumento del volumen de producción en esta cosecha sí se comienza a notar.

Miércoles 26 de agosto salió la gran sorpresa: Cecafé corrigió un “error en el sistema” y actualizó los volúmenes de exportación para agosto. La proyección de las exportaciones en agosto de repente subió de menos de 3 millones de sacos a cerca de 3.8 millones. 

Al cerrar el mes, las cifras preliminares de Cecafé reflejan un volumen exportado mayor todavía de 4.0 millones de sacos, un aumento del 32 % comparado con julio y del 24 % con respecto al de agosto de 2025. Se consideraba los datos de Cecafé de los más confiables en las estadísticas cafetaleras, pero ahora existen dudas, no se puede pasar por alto un millón de sacos. Los certificados de origen emitidos en agosto fueron por 3.8 millones de sacos, 14% más que en julio y 34% más que en agosto 2025.

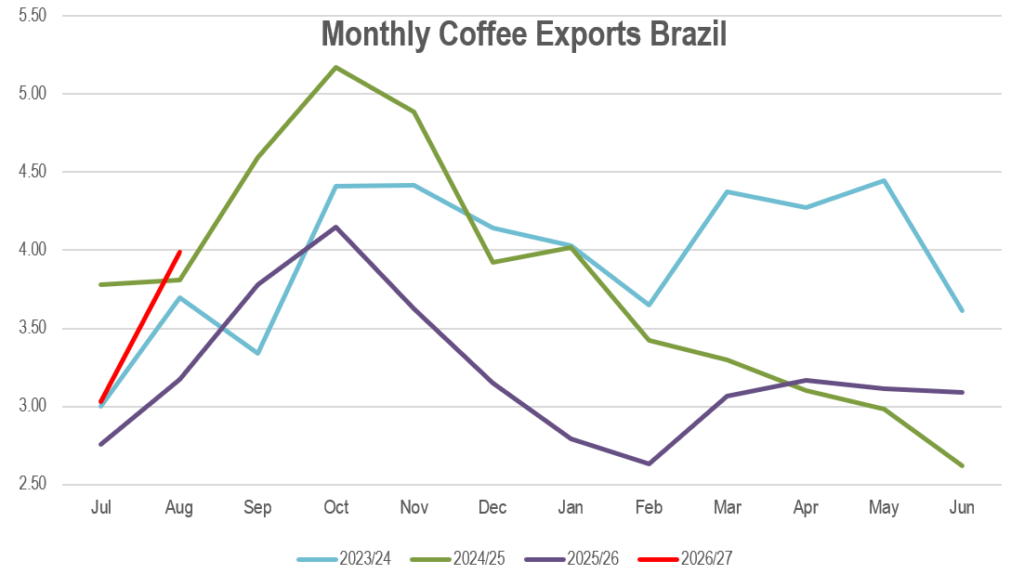
Las exportaciones de Brasil en 2025/26 (38.5 millones de sacos) estuvieron bastante por debajo de las de 2023/24 (47.4 millones) y 2024/25 (45.6 millones). El volumen del ciclo 2023/24 es el récord y en el año calendario 2024 se llegó a 50.6 millones de sacos, un promedio de 4.2 millones por mes, con un máximo de 5.2 millones en octubre.

En los primeros 3 días de septiembre ya se han emitido más de 600 mil certificados de origen. Quizás parece un tanto temprano para sacar conclusiones, pero a este ritmo se podría establecer nuevos récords. Al otro lado, se anticipa fuertes problemas con la logística de exportación si el volumen incrementa mucho.

Para darle seguimiento a la tendencia del precio, es muy importante monitorear el volumen mensual de exportación de Brasil publicado por Cecafé, esperando que no cometa otro “error” tan garrafal.

La corrección del “error”  cambió mucho el panorama. La agencia Archer Consulting cambió en su comentario semanal de “¿Dónde está la demanda global?” a “baño de sangre”. Parece cierto que las bodegas de café están repletas, hay noticias que los comerciantes ya no aceptan más café por falta de espacio.

La reacción en el mercado fue lo que se pudo esperar con estas noticias. El 26 de agostos el precio de Nueva York empezó a desplomarse y al viernes el precio ha bajado de más de 340 a menos de 300 centavos. Están circulando comentarios de que la cosecha 2026/27 de Brasil está aun mayor de lo que se había pronosticado, que estaría arriba de los 80 millones de sacos, 8 millones más del promedio manejado hasta el momento. 

El “pequeño error” costó una fortuna a varios operadores en el mercado, confiados de que el precio se iba a mantener alto. También creó conflictos entre compradores y sus proveedores, porque no cubrieron bien sus posiciones y buscan cómo deshacerse de fijaciones de contratos a precios altos.

Hay presión de venta sobre precios y diferenciales en Brasil, salvo para las mejores calidades. Esto último porque hay mucho café de mala calidad y granos pequeños. En el corto plazo, sin embargo, con la baja de los precios en Nueva York y Londres, los diferenciales de Brasil repicaron un poco. 

Productores de Perú reportan que el diferencial para Grado 1 ha subido hasta +70. Ya reportamos la vez pasada una baja considerable en el volumen de cosecha en Perú; se teme mucho incumplimiento de contratos.

Pronto comenzará la cosecha en México y Centroamérica y la cosecha principal en Colombia, que aumentará la presión sobre el precio de café Arábica, aunque la cosecha de Colombia va a ser menor que el año pasado y los problemas de logística a raíz del terremoto en el país continúan todavía.

Jos Algra es consultor internacional con más de 40 años de experiencia en café y trabajar con organizaciones de productores.

Este blog fue publicado originalmente en Claase:

The error

Commentary, Sep 05, Jos Algra

The price of coffee position December in New York reached a high of 345.65 on Tuesday, August 25, the highest price since July 6. However, the price peaked there and closed down 6.15 cents that same day. Wednesday was worse, with a loss of 13.33 cents, and Thursday another 12.50 cents. It continued to fall to a low of 289.75 on Thursday, September 3. On Friday the 4th, the decline halted for the moment; the price rose slightly and closed at 295.60.

The price of coffee is under pressure from the large volume of the Brazilian harvest, which has concluded and may be much larger than predicted. The sharp drop on Wednesday, August 26, is attributed to the correction of an “error” in the Cecafé system, which suddenly showed that Brazil exported 1 million more bags in August.

The price of Arabica in New York dragged down Robusta in London, which broke through the 3,600 dollar per ton support level and closed Friday at 3,430 $/MT.

The first question is whether the 295.20 floor will hold; it has already been tested three times, including on Thursday and Friday. If it gives way, the price could fall to 285.25, 263.50, and eventually 231.80.

To the upside, there is resistance at the 316.90-319.80 gap. In theory, gaps should always be filled, meaning the price should rise to that level, because there are outstanding buy and sell orders. In practice, this doesn’t always happen; it can take days, weeks, or even months for a gap to close. The market is highly oversold, as the stochastic shows, which could lead to a retracement.

Support: 295.15-295.20, 289.75, 285.25, 263.50, 256.90, 250.55 and 231.80. Resistance: 316.90-319.80 (gap) and 345.65.

In the Commitment of Traders report, combined Open Interest in futures and options fell by 1,373 contracts over the past two weeks, from 202,264 to 200,891. Open interest in futures alone decreased by 9,988 contracts, from 156,273 to 155,275 last Thursday. Daily volume averaged 29,500 contracts.

Net long positions held by funds fell by 7,899 contracts, from 15,044 to 7,415. Spreads, which reflect the degree to which each non-commercial trader holds combined long and short positions, decreased by 860 contracts, from 73,087 to 72,227.

Net long positions held by commercials increased by 2,119 lots, from 49,532 to 51,651. The short position of commercials decreased by 4,312 lots, from 101,009 to 96,697.

Index funds increased their net long position by 1,540 contracts, from 34,114 to 35,654.

They are reducing their bullish bets. Roasters are taking advantage of the lower price to lock in contracts. Producers are lowering their price fixations in response to the price drop, but at some point, they will have to fix their contracts against the December position. Many will have lost a lot by waiting to fix, hoping for a larger price increase.

In the August 23 blog post, “Change is on the horizon” I commented that Brazilian exports seemed to be staying at around 3 million bags in August, the same as in July and below the monthly volume from March to June. Well, nothing could be further from the truth; the increase in production volume for this harvest is indeed starting to be noticeable.

On Wednesday, August 26, a major surprise emerged: Cecafé corrected a “system error” and updated its export volumes for August. The projected exports for August suddenly jumped from less than 3 million bags to nearly 3.8 million.

At the close of the month, Cecafé’s preliminary figures reflected an even higher export volume of 4.0 million bags, a 32% increase compared to July and a 24% increase compared to August 2025. Cecafé’s data was considered among the most reliable in coffee statistics, but now doubts exist; a million bags cannot be overseen. Certificates of origin issued in August totalled 3.8 million bags, 14% more than in July and 34% more than in August 2025.

Brazilian exports in 2025/26 (38.5 million bags) were significantly lower than those of 2023/24 (47.4 million) and 2024/25 (45.6 million). The 2023/24 cycle volume is a record, and in calendar year 2024, exports reached 50.6 million bags, an average of 4.2 million per month, with a peak of 5.2 million in October.

In the first three days of September, more than 600 thousand certificates of origin have already been issued. It may seem a bit early to draw conclusions, but at this rate, new records could be set. On the other hand, significant problems with export logistics are anticipated if the volume increases considerably.

To track the price trend, it is crucial to monitor Brazil’s monthly export volume published by Cecafé, hoping they don’t make another such monumental “error.”

The correction of the “error” significantly altered the landscape. Archer Consulting changed its weekly commentary from “Where is the global demand?” to “bloodbath.” It seems certain that coffee warehouses are overflowing; there are reports that traders are no longer accepting coffee due to lack of space.

The market reaction was predictable given this news. On August 26, the New York price began to plummet, and by Friday, it had fallen from over 340 cents to less than 300 cents. Rumours are circulating that Brazil’s 2026/27 harvest is even larger than previously forecast, exceeding 80 million bags, 8 million more than the average figure reported so far.

This “small error” cost several market operators a fortune, as they were confident that prices would remain high. It also created conflicts between buyers and their suppliers, who failed to adequately hedge their positions and are now seeking ways to unwind high-priced contracts.

There is selling pressure on prices and spreads in Brazil, except for the highest grades. This is because there is a significant amount of low-quality coffee and small beans. In the short term, however, with the drop in prices in New York and London, Brazilian spreads have widened slightly.

Producers in Peru report that the spread for Grade 1 coffee has risen to +70%. We previously reported a considerable decrease in the Peruvian harvest volume; there are serious concerns about contract defaults.

The harvest will soon begin in Mexico and Central America and the main harvest in Colombia, which will increase pressure on the price of Arabica coffee, although Colombia’s harvest will be smaller than last year and logistical problems following the earthquake in the country are still ongoing.

Jos Algra is an international consultant with more than 40 years of experience in coffee and working with producer organisations.

This blog was originally published in Spanish in Claase:
Progreso is hiring an Agroforestry Expert in Peru

For more information, please see the ToR (in Spanish)

Progreso is looking for an Agroforestry Expert to join the team in Peru, working across Cajamarca, Amazonas, and San Martín in a hybrid role. The position sits within our coffee and cocoa work in the region, reporting to the Program Manager LATAM and coordinating closely with the Country Manager in Peru.

The role is hands-on: designing agroforestry systems that combine coffee and cocoa with productive tree cover, and thinking through how certification frameworks (Fairtrade, Organic, Rainforest Alliance and others) and the EUDR shape benefit-sharing on the ground. Beyond design, the expert will monitor ongoing projects, set up KPIs and OKRs, support partnership negotiations with public and private partners, and work alongside colleagues in Colombia and Nicaragua to share lessons across the region.

We’re looking for someone with at least five years of experience implementing agroforestry or agroecology projects with coffee or cocoa producer organizations, a degree in agricultural, agronomic or forestry engineering, and postgraduate training in agroforestry or project management. Willingness to travel to project areas (around 40% of the time) is required.

CVs are open from August 27 to September 11, sent to patricia@progreso.nl and christie@progreso.nl. Virtual interviews for shortlisted candidates run September 15–16, with hiring expected by September 21.

If you know someone who fits this profile, this is a good moment to pass it along.

Español

Progreso busca un/a Experto/a en Agroforestería para Perú

Para más informacion, por favor, vea aquí

Progreso está buscando un/a Experto/a en Agroforestería para sumarse al equipo en Perú, con sede en Cajamarca, Amazonas o San Martín, en modalidad híbrida. El puesto se enmarca en nuestro trabajo con café y cacao en la región, reportando a la Program Manager LATAM y coordinando de cerca con la Country Manager de Perú.

Es un rol de terreno: diseñar sistemas agroforestales que combinen café y cacao con cobertura arbórea productiva, y pensar cómo los marcos de certificación (Fairtrade, Orgánico, Rainforest Alliance y otros) y la ley EUDR condicionan la distribución de beneficios en la práctica. Además del diseño, la persona seleccionada monitoreará los proyectos vigentes, definirá KPI y OKR, apoyará la negociación de alianzas con socios públicos y privados, y trabajará junto a los equipos de Colombia y Nicaragua para compartir aprendizajes entre países.

Buscamos a alguien con al menos cinco años de experiencia implementando proyectos de agroforestería o agroecología con organizaciones de productores de café o cacao, título en Ingeniería Agrícola, Agronómica o Forestal, y una maestría o especialización en agroforestería o gestión de proyectos. Se requiere disponibilidad para viajar a las zonas de intervención (alrededor del 40% del tiempo).

La recepción de CV está abierta del 27 de agosto al 11 de septiembre, a los correos patricia@progreso.nl y christie@progreso.nl. Las entrevistas virtuales para los candidatos preseleccionados serán el 15 y 16 de septiembre, con contratación estimada para el 21 de septiembre.

Si conoces a alguien con este perfil, es un buen momento para compartirlo.

Change is on the horizon

During the week, the coffee price of December position in New York rose to a high of 335.50, the highest price since July 6. On Friday, however, it fell 6.65 cents and closed at 322.65. Friday, August 21, was First Notice Day for September, which has a premium of more than 36 cents over December; the coffee shortage in the short market continues.

Continue reading

El cambio acecha

En la semana el pecio de café posición diciembre en Nueva York subió a un máximo de 335.50, el precio más alto desde el 6 de. El viernes, sin embargo, cedió 6.65 centavos y cerró en 322.65. Viernes 21 de agosto fue First Notice Day para septiembre, que tiene un premio de más de 36 centavos sobre diciembre; la escasez de café en el corto plaza continua.

Continue reading

¿Hay vuelta al pasado?

En la quincena el pecio de café posición diciembre en Nueva York se movió entre un máximo de 323.75 y un mínimo de 302.60. El viernes subió 9.8 centavos para cerrar en 315.90. Septiembre subió 13.90 centavos a 335.55. El mercado sigue fuertemente invertido, sobre todo entre las primeras posiciones, reflejando que la escasez de café en el corto plaza continua.

Continue reading

Return to the past?

In the first half of the month, the price of coffee December position in New York fluctuated between a high of 323.75 and a low of 302.60. On Friday, it rose 9.8 cents to close at 315.90. September rose that day 13.90 cents to 335.55. The market remains heavily inverted, particularly for the nearby contracts, reflecting the ongoing short-term coffee shortage.

Continue reading

OpenAtlas, Gosling Coffee and Progreso Pioneer EUDR Compliance with Cooperative Data

Original press release posted at Open Atlas

Amsterdam, June 2026 – OpenAtlas, Gosling Coffee, and Progreso today announced the successful completion of a pioneering European Union Deforestation Regulation (EUDR) deforestation risk assessment covering five coffee producer organisations across Uganda, Rwanda, and Peru; representing 3,074 smallholder farmers and over 2,358 hectares of farmland, using geodata collected through Beyco Farmer Platform, Progreso’s digital management system for cooperatives, which ensures that data is generated, owned, and managed by producer organisations themselves.

The collaboration, marks one of the first end-to-end EUDR compliance assessments in which the underlying data belongs to, and benefits, the producer organisations themselves. Analysis was conducted via OpenAtlas’s API-based deforestation risk platform, enabling automated assessment at scale against EUDR criteria.

Results across all five cooperatives of Busongora, Rwandaro, Rutas del Inca, TUK, and Nyampinga showed 99.7% of analysed farms classified as low deforestation risk, covering 99.9% of the total area assessed. The assessment demonstrates how producer organisations can generate the geolocation and risk data required under the EUDR, helping maintain access to EU markets while reducing compliance burdens across supply chains.

“We wanted to be ahead of EUDR rather than scrambling when it comes into force,” said Bonnie van Poortvliet, CEO of Gosling Coffee. “Working with Progreso and OpenAtlas felt like the right way to do that, using data that belongs to the cooperatives, not to us, and building something that benefits them as much as it benefits us.”

“I think the results speak for themselves: smallholder farmers around the world are facing exclusion from the European Union common market not because they’ve done anything wrong, but because they lack the resources and tooling to prove that they haven’t” Harry Marshall, CEO & Co-founder of OpenAtlas. “Our collaboration with Progreso and Gosling Coffee is a first step in managing that gap through partnerships” 

“This collaboration between Progreso, OpenAtlas, and Gosling Coffee demonstrates that EUDR compliance does not have to be something imposed on producer organisations. With the right tools and partnerships, cooperatives can take the lead in managing and owning their data, while buyers and service providers help unlock the resources needed to meet new regulatory requirements. We believe that strong data capability in producer organisations goes far beyond compliance, it creates long-term value, resilience, and empowerment.”

About the partnership

Gosling Coffee, a Dutch specialty roaster, has sourced from Progreso’s cooperative network in East Africa and Latin America for several years. Progreso has supported participating cooperatives with technical assistance and digital traceability infrastructure. OpenAtlas provided the geospatial intelligence layer — translating cooperative plot data into regulatory-grade EUDR risk signals through its API.

The assessment covered cooperatives in three countries, with all data analysed to date consisting of largely low deforestation risk.

About OpenAtlas

OpenAtlas is an Amsterdam-based geospatial intelligence company transforming satellite and earth observation data into automated supply chain risk signals. Its API-first platform helps companies navigate regulatory requirements including EUDR, with a focus on scalable, data-sovereign compliance infrastructure.

About Gosling Coffee 

Gosling Coffee is a Dutch specialty coffee roaster sourcing directly from cooperative partners across East Africa and Latin America. They believe that equal trade in a transparent way is going to make the coffee industry sustainable. With direct contracts between cooperatives and Gosling Coffee and for instance this collaboration, they make a real difference for farmers they work with. 

About Progreso

Progreso is an international development organisation based in The Netherlands, that strengthens farmer-owned cooperatives and producer organisations across Latin America, Africa, and Asia. Through Technical Assistance, access to finance, business development services, and digital solutions such as Beyco, Progreso helps producer organisations improve their resilience, competitiveness, and long-term sustainability. Its approach focuses on empowering cooperatives to create value for their members and play a leading role in sustainable supply chains.

Progreso Côte d’Ivoire: a resurgence of activity

Written by Natan Yao

After a period of relative calm, the Progreso Côte d’Ivoire division has seen a resurgence of activity in recent weeks, spanning agroforestry, income diversification, and a new technical assistance partnership.

Zaranou: progress and lessons in agroforestry transition

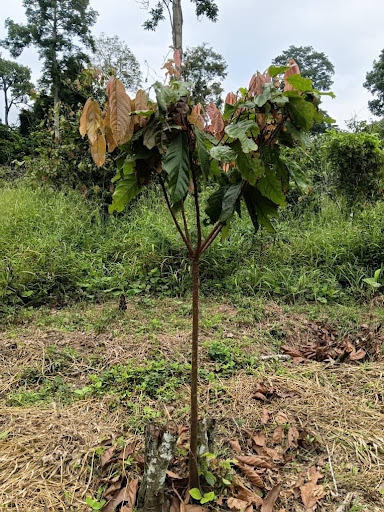
At a time when climate challenges and the sustainability of agricultural value chains sit at the heart of our priorities, the project in Zaranou, run with CAADI and CAMAYE, focuses on reforestation and cocoa regeneration as a way of restoring ecosystems and strengthening producers’ resilience. Following its initial implementation phase, the picture is mixed but rich in lessons.

Cocoa regeneration has gone well. Plots have received regular, rigorous maintenance, pruned cocoa trees and young seedlings and banana trees are growing strongly, and plant health is well managed, laying a solid foundation for a gradual return to production.

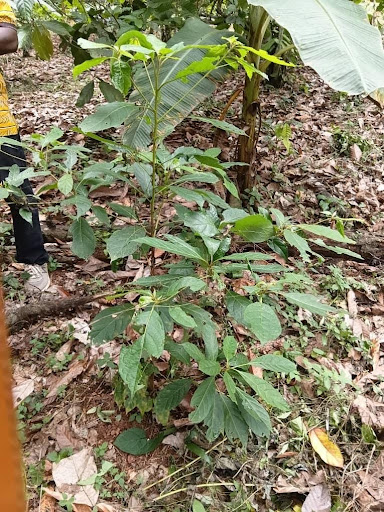
Reforestation has proven harder. The phase developed 4 hectares with four pioneer producers, against an initial target of 10, and ran into real constraints: schedule delays from funding gaps and unpredictable weather, and a seedling survival rate of only around 30 percent, driven mainly by difficult access to certain plots and a lack of post-planting maintenance, particularly for species like petit cola.

Based on these findings, Progreso Côte d’Ivoire and its partners are strengthening the monitoring framework between June and September, with three priorities: rehabilitating and expanding the area, by replacing dead seedlings across the existing 4 hectares and securing 6 new ones to reach the 10-hectare goal; stepping up on-the-ground support, through monthly and quarterly monitoring reports and greater producer accountability for plot maintenance; and improving performance and diversification, targeting a survival rate above 70 percent, introducing suitable forest and fruit tree species, and continuing phytosanitary care for cocoa regeneration.

From beans to mushrooms: diversifying income in Ouassakro

Faced with climate uncertainty and fluctuating cocoa prices, relying on a single crop is no longer enough to secure the resilience of rural communities. With that in mind, Progreso and the SCAOD-SCOOPS cooperative took a decisive step forward in Ouassakro, in the Diégonéfla department, where a large-scale training and technical support mission ran from July 27 to 31. The goal: turn mushroom cultivation into a real driver of financial empowerment alongside cocoa.

Mushroom cultivation complements cocoa well. Where cocoa is highly seasonal with widely spaced harvests, mushrooms offer a regular, fast-turnaround income stream, and one that creates direct ecological synergy with cocoa farming: cocoa husks, once discarded or left to rot, are reused as a rich growing substrate, turning agricultural waste into a resource that creates value.

The results were concrete. More than 65 producers were trained across five localities (Ouassakro, Kongokro, N’zuekro, Tiégba, and Bronda), producing over 250 bags of growing medium using three formulations built on local residues, including cocoa husks, rice straw, corn cobs, and rice bran. Producers gained full command of the production cycle, from substrate preparation and pasteurization through seeding, incubation, harvesting, and packaging.

Beyond the technical results, the initiative lays the groundwork for scaling up the Ouassakro mushroom farm. By generating alternative income year-round, farming families strengthen their food security and financial stability. Next steps include setting up three Village Savings and Credit Associations to organize community savings and sustain the activity long-term, alongside a rigorous technical monitoring plan carried out by trainers and farmer inspectors.

A new two-year technical assistance agreement

With the previous round of technical assistance having ended in March 2026, Progreso remained in ongoing discussions with its long-standing partner, Rabobank Foundation, exchanges that continued both in person at the CHOCOA conference in Amsterdam and online. Those conversations led to a new agreement, signed on July 22, to resume technical assistance for six cooperatives in the cocoa sector.

Alongside traditional activities such as improving governance, strengthening the quality of financial data, and developing business plans to secure financing, the program will also focus on income diversification and financial education. The team is preparing to begin work with all six cooperatives in August 2026, starting with data collection for the baseline study.