Commentary, Nov. 15, Jos Algra
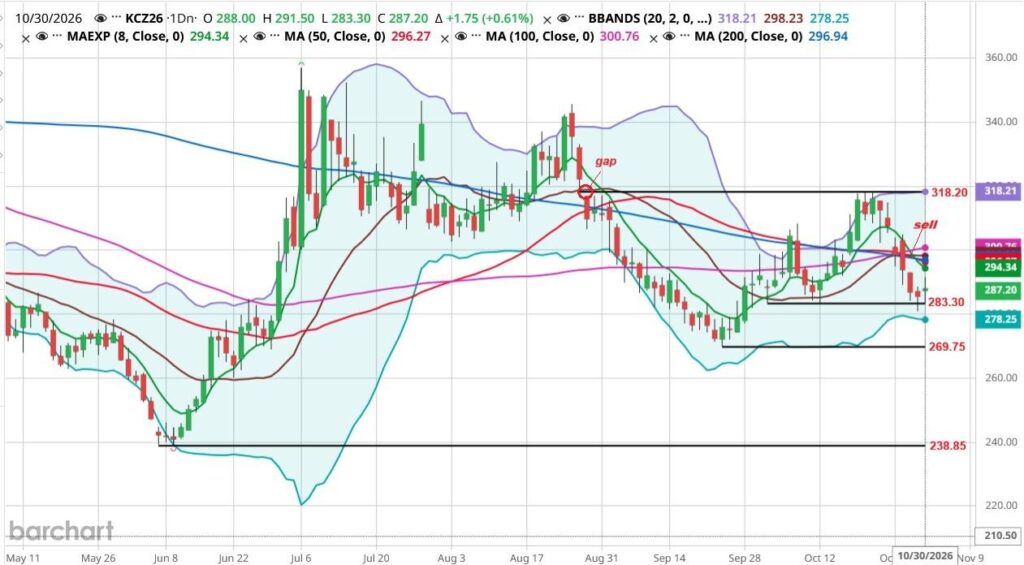
The price of coffee in New York continued its downward trend, hitting a low of 262.15 last Wednesday. On Thursday, it rose by 9.90 cents, and on Friday, it reached a high of 279.20 before closing at 273.50 cents.
Coffee prices remained under pressure due to the outlook for high production volume in Brazil’s new cycle, the weakness of the Brazilian real against the U.S. dollar, and the broader macroeconomic situation.
We had previously noted that prices might begin to decline, starting in November, a time when forecasts for Brazil’s 2027/28 harvest become clearer, and when new harvest coffee begins to arrive from Mexico and Central America.
The discounts for future positions have narrowed once again: 5.30 cents between the December and March contracts, and 4.30 cents between March and May. Short-term scarcity persists; as of Friday, certified inventories had fallen to 211,321 bags, the lowest level since February 1999. However, there are 162,899 bags from Brazil currently awaiting grading, in addition to the 76,277 bags already certified.
This coffee could trigger a shift in price formation (see our previous blog Does the roller coaster continue?) and potentially signal the end of the backwardation (see the October 18th blog, The End of Backwardation?).
The price broke through the support level near 270 but held above 260. It recovered on Thursday, closed the gap between 274.95 and 277.40, and tested the resistance level at 280, before contracting to close at 273.50 on Friday. The question is whether a new bullish trend is beginning and whether the price will manage to surpass 280 cents again, and then 300. On the downside, there are support levels at 260 and 240; one should remain vigilant when it comes to fixing contract prices.
Support: 269.75, 260.15, and 238.85. Resistance: 279.20, 288.00 (pivot), 297.35, 304.90, 304.00–305.30 (gap), and 318.20.
The Commitment of Traders report has only been updated up to November 3rd. We do not know how the various market participants have positioned themselves over the last week and a half. However, between October 27 and November 3, funds increased their net short position by 4,250 contracts, from 1,019 to 5,269, and, given the subsequent decline in prices, it is reasonable to assume that they have expanded this position even further.
This confirms a downturn in market sentiment within the New York coffee market, as was anticipated two weeks ago (see blog Does the roller coaster continue?).
Open Interest in futures contracts also confirms this, showing that the trend persisted into the following week. It fell by 23,557 contracts, from 170,306 two weeks ago to 146,749 as of last Thursday. Daily volume averaged slightly over 52 thousand bags.
Rabobank projects a surplus of 9–10 million bags for the current cycle. For the 2027/28 cycle, the preliminary forecast points to a surplus of 1.3 million bags. However, a significant drop in production across India, Vietnam, and Indonesia, linked to the El Niño phenomenon, combined with a stronger recovery in consumption, could shift this outlook to a deficit of 5 million bags.
Conversely, a stronger-than-expected performance during Brazil’s off-year could push the forecast toward a surplus of 4 million bags. Furthermore, a resolution to the crisis in the Red Sea could reduce the volume of inventory in transit, thereby increasing available stocks.
Under the first scenario, Rabobank estimates that inventories would rise by 10%, reaching more than 40% of global consumption, while the price of Arabica coffee would decline to approximately 245 cents over the course of 2027. In the second scenario, with a deficit of 5 million bags, the price could reach around 350 cents. In the third scenario, with a surplus of 4 million bags, the price could fall to 200 cents or less.
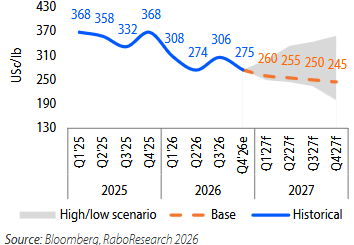
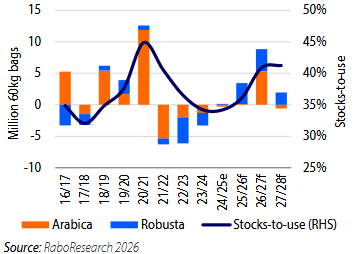
The entry into production of new areas in several coffee-producing countries, combined with a high-yield cycle in Brazil expected for 2028, should exert downward pressure on prices starting in the second half of 2027, unless setbacks occur during the flowering phase of the Arabica coffee crop in Brazil for the 2028/29 cycle, which begins in September 2027.
Since January 2024, maritime transport through the Red Sea has been severely affected by hostilities from the Houthis in Yemen. Shipping via the Red Sea and the Suez Canal, the most critical route connecting Asia, East Africa, and Europe, has declined by 60%. Coffee shipments from India, Indonesia, and Vietnam, as well as from coffee-producing nations in East Africa, have been particularly impacted.
The alternative, rerouting vessels around the African continent, adds 2–3 weeks to transit times, creates significant logistical challenges (such as container allocation and transshipments), and drives up costs, further compounded by rising fuel prices. Additionally, this has resulted in an unquantified volume of coffee remaining in transit.
Transport along this route gradually began to return to normal, with volumes in August of this year increasing by 27%, the highest level since December 2023. However, in October, the Houthis took control of the Bab al-Mandab Strait, located between Yemen and the Horn of Africa (Djibouti and Eritrea), leading once again to significant uncertainty regarding shipping along this route.
According to data from the USDA’s Foreign Agricultural Service (FAS), coffee consumption in China has grown significantly over the last 25 years, from 131 bags in 2002 to an estimated 6.8 million bags this season, a figure nearly equal to consumption in Japan, currently the largest coffee-consuming market in Asia.
Over the past five years, the average annual growth rate has been 6.5%, 5.8 times more than the global average of 1.1%. Per capita consumption remains very low, and the growth potential is enormous, making China one of the most attractive markets for the coffee industry and for coffee-producing nations.
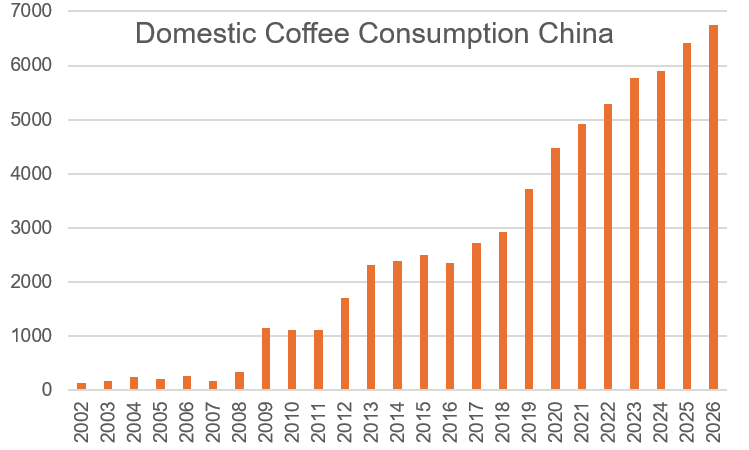
In thousands of bags
China also produces and exports coffee. Production grew from 325 thousand bags in 2002 to 1.9 million over the last three cycles, with 1.2 million of those being exported. To meet domestic demand, China must import 6 million bags.
Previously, China primarily imported processed coffee, roasted coffee from the United States, and soluble coffee from Malaysia and other countries in the South Asian region. However, as consumption has grown, a domestic roasting industry has emerged, and the share of green coffee imports has increased.
By 2026, 59% of imports, amounting to 4 million bags, consisted of green coffee, 67% of which was Arabica. The primary suppliers are Brazil (42%), Colombia (21%), Vietnam (13%), and Ethiopia (9%). The types and origins of these coffees point to a relatively high proportion of higher-quality beans. This is also evident in the processed coffee segment, where 22% consists of specialty coffee (organic and single-origin), a notably high percentage compared to more mature markets.
As in many other markets, Chinese consumers began by drinking instant coffee, which accounted for 80–90% of total consumption. The next phase involved the introduction and expansion of coffee shop culture in major metropolitan areas, driven by foreign chains such as Starbucks and Costa Coffee. Shanghai, with over 11 thousand coffee shops, ranks first in the world; the city’s average per capita coffee consumption is 106 cups, compared to a national average of 29.
Since 2023, homegrown chains like Luckin Coffee and Cotti Coffee have begun to displace international brands. They are better attuned to local consumer preferences, which vary significantly across a country as vast as China, offer more affordable products, demonstrate greater innovation in their use of digital technology, leveraging Artificial Intelligence for decision-making and adapting compact retail formats to better suit customer preferences.
These chains are more effective at winning over consumers and more efficient at scaling their networks. They are successfully penetrating mid-sized cities, of which there are many in China, thereby further expanding the country’s coffee market.
Concurrently, tea shops have begun adding coffee to their offerings to create an additional revenue stream, further boosting consumption. Chains such as Goodme and MIXUE (Lucky Cup) now generate 15–20% of their revenue from coffee sales.
Coffee shops remain the primary driver of growth in coffee consumption—with sales increasing at an annual rate of 21.7% between 2021 and 2025—but the market is diversifying. The range of opportunities to consume coffee is broadening, and the beverage is becoming increasingly integrated into consumers’ social lives. This growth is intensifying competition, placing greater pressure on companies to continue innovating and improving operational efficiency.
The unique characteristics of China’s coffee industry, mentioned above, position it to expand its operations into neighbouring countries and capitalise on the robust growth of the middle class there. This does not mean a simply copy – paste of the Chinese model; rather, as was the case in China, it requires adapting to local conditions and taking root. This process calls for local partners who can provide consumer insights, distribution networks, and capital, areas in which franchises will play a significant role.
Jos Algra is an international consultant with more than 40 years of experience in coffee and working with producer organisations.
This blog was originally published in Spanish in Claase: https://claase.org/analisis-de-los-precios-del-cafe